When the Rhine Runs Low: How Weather Reshapes European Barge Logistics
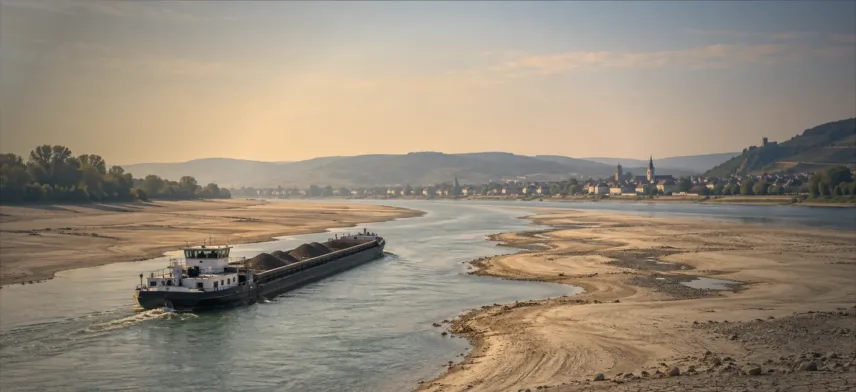
Key message: On 1 October 2026 the Rhine gauge at Kaub, the bottleneck between the ARA ports and southern Germany, France and Switzerland, read −6 cm – the lowest reading on record, below the previous record of 25 cm set in October 2018. Dutch inland shipping moved 18.8% less cargo in August than a year earlier, transit through the Netherlands halved, and barge deliveries of oil products to Basel fell 79%. This post sets out what the data show and what they mean for anyone moving bulk commodities through North-West Europe.
Note on the data. Figures below are drawn from the official Kaub gauge record (WSV PEGELONLINE, daily means computed from 938,726 raw 15-minute readings, 1 January 2000 to 9 October 2026), Dutch inland-shipping statistics (CBS StatLine table 85528NED), Swiss Rhine port bulletins (Port of Switzerland) and published freight rates and surcharge schedules (Argus, S&P Global, Hapag-Lloyd, Maersk). Raw Kaub readings are not yet validated and may differ slightly from official figures; CBS data from 2019 onward are preliminary; one freight figure is taken from a press report of S&P Global data rather than the primary source. 2026 figures cover the year to date and will be revised as later months are published.
This post continues our logistics and market-infrastructure series for procurement and trading teams. It sets out how severe the 2026 low-water episode on the Rhine has been against 25 years of gauge history, what it did to measured cargo volumes and freight rates, and what that means for anyone who depends on the river – directly or indirectly.
A record broken in August, and again in October
Kaub first fell below the 2018 record of 25 cm on 5 August, according to the Waterways and Shipping Office in Bingen. By 17 August the raw gauge data show about 5 cm. Late-August rain brought only a short recovery: from 25 September readings were at or below zero on 11 days, with the low of −6 cm on 1 October. On the morning of 9 October the gauge still read between 3 and 9 cm.

Apart from a flood from mid-February to early March, the river was below its 2000-2025 median on every day of 2026 so far. From 1 July to 9 October it ran below the lowest level recorded on the same calendar day in any year since 2000 on 88 of 101 days.
Duration is what hurts logistics. The daily mean has been below 80 cm every day since 22 July: 80 days in a row by 9 October, against a longest run of 67 days in 2018. Below 40 cm, where the Rhineland-Palatinate chambers of commerce say barging no longer makes economic sense, 2026 already counts 62 days, twice the 31 days of 2018.

Such episodes used to be rare. Between 2000 and 2025 only 4.2% of days had a daily mean below 80 cm, and only three years (2003, 2018 and 2022) saw it drop below 40 cm. Copernicus reports exceptionally low summer flows along almost the entire length of the Rhine, with record lows at several locations.
Why one gauge decides the load
Kaub is a reference gauge, not a depth reading. At the official equivalent low-water level (GlW) of 77 cm, the authorities maintain a 1.90 m navigation channel on this stretch (PEGELONLINE). Below that the channel loses depth roughly centimetre for centimetre, so a reading of 0 cm leaves about 1.1 m (our estimate from the official reference values). In late September the WSA Bingen said most vessels can no longer operate at channel depths of 1.50 or 1.20 m.
The Middle Rhine between Mainz and St. Goar is the shallowest section of the route, so it sets the load for the whole voyage between the ARA ports and the Upper Rhine. Barges sail part-loaded, and more of them are needed for the same tonnage:
· Rotterdam: barge loading fell from about 70% to about 35%, and roughly 100 extra barges called each week (ANP, 5 August).
· Duisburg: ship calls rose 50-60%, while vessels on some stretches ran at about one third of normal utilisation (duisport, 21 August).
· Netherlands overall: the average load per trip in August was 1,299 t, against about 1,500 t in most Augusts since 2012, while the number of trips per vessel rose 3.4% (CBS).
Carrier contracts key off the same gauge. Hapag-Lloyd, for example, no longer guarantees barge transport to terminals south of Koblenz once Kaub is at or below 80 cm.
What happened to volumes
Netherlands. Dutch statistics are the fastest official read on Rhine traffic. In August 2026 Dutch inland shipping moved 21.8 Mt, 18.8% less than a year earlier; July was down 9.3% (CBS). In our check of the monthly series, August is the lowest month since it began in 2012. Demand was not the problem: in the first half of 2026 volumes were 6.3% above 2025.

The split points to the river. Domestic Dutch traffic was flat, while transit through the Netherlands halved. Cargo to Germany fell 39.7% and cargo from Germany 49.5%. Dry bulk dropped 27.3%, liquid bulk 8.1%.
The 80 cm threshold. Matching 98 months of CBS data to the Kaub gauge shows how non-linear the effect is. While Kaub averages above 80 cm, cross-border and transit tonnage is on average within 2% of its seasonal norm, though single months vary by up to +/-11%. In the five months averaging 40-80 cm it was 11% lower on average (between 1% and 15%); in August 2026, at an average of 33 cm, it was 24% lower. Domestic traffic, which does not pass the bottleneck, shows no systematic decline.

It points the same way as IfW Kiel’s analysis of 2018: a month with Kaub below 78 cm on every day cut German inland waterway tonnage by just over 20% compared with a preceding month without low water.
Upstream is hit hardest. At the Swiss Rhine ports near Basel, total waterside throughput fell 32% year on year in July and 66% in August. Mineral oil receipts, over 40% of the ports’ waterside throughput in January-August 2025, fell 42% and 79% (Port of Switzerland).

Germany. Destatis publishes monthly barge statistics with a lag of about three months, so the low-water months will show only later this year. The baseline was already weak: German inland waterway transport fell to 171.6 Mt in 2025, the lowest since 1990, and 71% of its cross-border volume moves to and from the ARA ports (VerkehrsRundschau, citing Destatis). Total Rhine traffic was 281.9 Mt in 2025 (CCNR).
What it costs
When a barge carries a third of its normal load, the cost per tonne rises several-fold. Published tanker rates show it:
· ARA to Karlsruhe: a record €215/t on 13 August. Argus called the rate “largely theoretical” because so few cargoes moved.
· ARA to Basel: up from €165/t to €215/t between 11 and 18 September, on Spotbarge data reported by S&P Global.
· ARA to Karlsruhe, early October: around €200/t, nearly ten times the January level (S&P Global, as reported by Cyprus Shipping News).
Container surcharges are tied to the Kaub gauge in published bands. Hapag-Lloyd charges €165 per 40′ box to terminals south of Koblenz at 81-90 cm, €380 at 71-80 cm and €1,280 at 40 cm or below. Maersk added a €625 per container contingency surcharge on 7 August for cargo routed via its Andernach inland terminal, on top of its existing low-water surcharge.

The cost curve is convex. A fall from 150 cm to 81 cm adds €115 per 40′ box; a further fall of 41 cm, to 40 cm, adds another €1,115.
What it means for commodity flows in NWE
For physical traders and industrial buyers, low water on the Rhine is now a recurring operating condition. Five practical points:
1. Price the river into inland deals. When barge freight moves from tens of euros to €200/t, it can outweigh the trading margin on inland deliveries of fuels, vegetable oils, feedstocks or petcoke. Quote inland delivered prices with a freight adjustment linked to the Kaub gauge rather than as a flat number.
2. Write the gauge into the contract. Name the reference gauge (Kaub for destinations upstream of Koblenz, including the Main and the Upper Rhine; Cologne for Koblenz to Cologne; Duisburg-Ruhrort or Emmerich for the Lower Rhine), the reading that applies (source, time, loading or departure date) and the surcharge bands. Define what happens below the carrier’s no-guarantee level: quantity tolerance, laycan extension, part deliveries or cancellation. Make sure sale terms pass through what the barge charter allows.
3. Plan stocks for a longer season. In 2018 the longest stretch below 80 cm ran from late September to early December; in 2022 from mid-July to late August. In 2026 it started on 22 July and is still running. Building inland stocks before July and keeping flexibility into November is a sensible base case.
4. Secure capacity early and accept smaller lots. Low-draught tonnage and split parcels keep cargo moving, at a price. Rail and road take only part of the load: in early August the Port of Rotterdam saw no measurable shift to either.
5. Track forecasts, not just today’s reading. WSV and the Federal Institute of Hydrology (BfG) publish Kaub forecasts for the next 48 hours and longer-range estimates through PEGELONLINE and ELWIS.
The structural fix is years away. Deepening the Middle Rhine channel by 20 cm, from 1.90 m to 2.10 m at low water, has been on the political agenda since 1992. Only one of three sections is in the approval process, and the inland shipping association BDB cites 2033 for completion (ingenieur.de).
Outlook
On 9 October Kaub was still reading in single digits. On 30 September the BDB said the river would need about two weeks of continuous rain, mainly in south-west Germany. If the gauge stays below 80 cm until 29 October, 2026 will pass the 110 days of 2018, the worst full year since 2000.
The next data points are the CBS figures for September, the September bulletin from the Swiss Rhine ports and, later in the year, the German monthly statistics for July to September.
The longer view matters more. Since 2000, the daily mean at Kaub has fallen below 40 cm in only four years, and three of them came in the last nine. Supply chains in North-West Europe should treat low water as a recurring season, not a rare event.
Methodology and sources
· Kaub water levels: 938,726 raw 15-minute readings from WSV PEGELONLINE, 1 January 2000 to 9 October 2026, aggregated to daily means. Raw readings are not yet validated and may differ slightly from official figures. Reference values (GlW 77 cm, record low 25 cm) are the official PEGELONLINE gauge values. Calendar-day comparisons exclude 29 February.
· Volumes: CBS StatLine table 85528NED, monthly, July 2018 to August 2026 (preliminary from 2019). The seasonal norm is the 2019-2025 average for the same calendar month; bands use the monthly mean Kaub level. Dutch cross-border and transit flows serve as a proxy for Rhine traffic and include some routes that avoid the Rhine. The two lowest bands contain only six months.
· Basel: Port of Switzerland monthly bulletins, January to August 2026.
· Freight and surcharges: rates as published by the sources below; one figure is taken from a press report of S&P Global data.
This note is for information only and is not trading or investment advice.
Sources: WSV PEGELONLINE (Kaub gauge reference values and API documentation); CBS StatLine 85528NED and CBS news release, 9 September 2026; Port of Switzerland statistics and monthly bulletins, August 2026 bulletin; Copernicus Climate Change Service, river flow, August 2026; VerkehrsRundschau on Destatis 2025 inland waterway data, March 2026; CCNR press release, June 2026; IfW Kiel, low water and inland shipping, 2018; IHK-Arbeitsgemeinschaft Rheinland-Pfalz via epd, 29 July 2026; ANP, 5 August 2026; duisport press release, 21 August 2026; Argus, 13 August 2026; S&P Global, 18 September 2026; Cyprus Shipping News, 7 October 2026; Hapag-Lloyd, Rhine low water surcharge update, 2026; Maersk, Andernach contingency surcharge, 7 August 2026; dpa via inFranken, 30 September 2026; ingenieur.de, 14 August 2026.
Procurement takeaway
The 2026 season confirms what procurement teams have long suspected but could rarely quantify: Rhine water levels are not background risk, they are a direct, measurable driver of freight cost and cargo availability. A record low at Kaub translated into a near-19% drop in Dutch barge volumes, a two-thirds collapse in oil-product deliveries to Basel, and container surcharges that rise more than 2x the moment the gauge crosses 80 cm. None of it is unprecedented in kind – 2018 and 2022 showed the same mechanism – but 2026 has already run longer than either, and the data since 2000 show low water arriving more often, not less.
Prime Elements sources and moves petrochemical, petcoke and agricultural feedstocks across a European logistics network that includes Rhine and ARA-region barge routes among its transport options. Where a customer’s supply chain depends on river-based logistics, we work with them on realistic contingency planning – alternative transport modes, delivery timing and inventory positioning – so that a weather-driven disruption on the river is a planned-for scenario rather than a surprise.